The minutes after a collision can feel disorienting. You may be checking for injuries, moving your vehicle out of traffic, calling law enforcement, and trying to reach family – all before you have had time to think about insurance. Knowing how to file auto claim paperwork in the right order can help protect your safety, support a smoother review, and give your insurer the information needed to evaluate the loss.
An auto claim is a request for coverage under an insurance policy after an accident, theft, weather event, vandalism, or other covered loss. The process is not the same for every situation. Your available coverage, the cause of loss, the parties involved, and your state’s rules can all affect what happens next. Still, a calm, well-documented first response puts you in a stronger position.
Start at the Scene, If It Is Safe
Your first responsibility is safety, not paperwork. Call 911 when someone is injured, a vehicle cannot be moved safely, there is a possible crime, or local law requires police reporting. If you can do so safely, move vehicles away from active traffic, turn on hazard lights, and avoid discussing fault with the other driver.
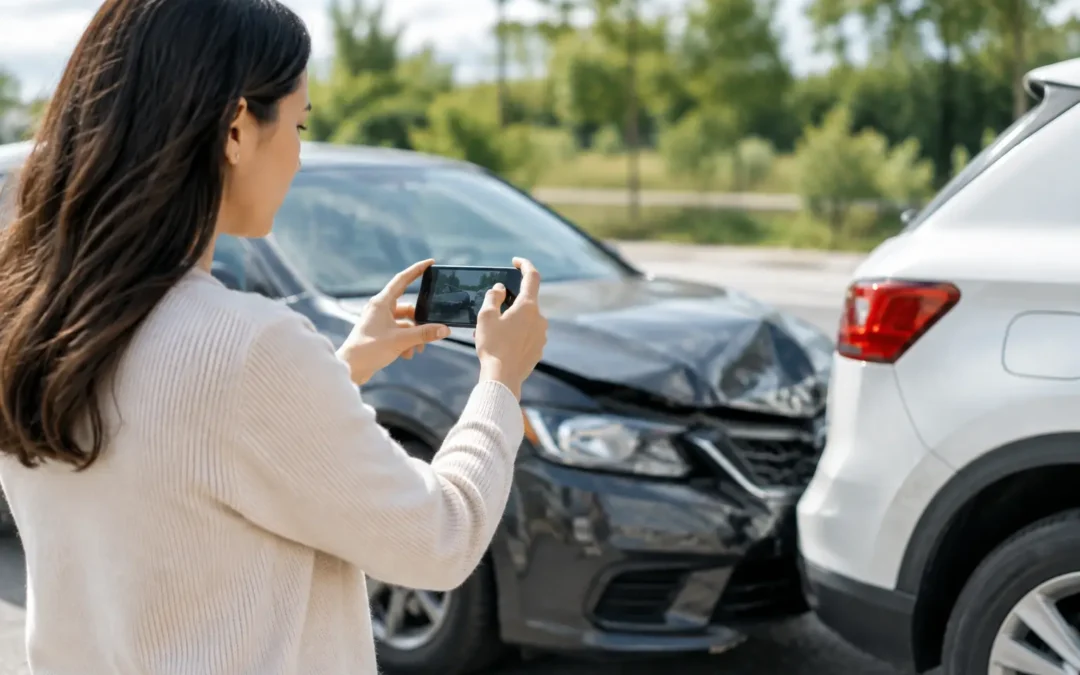
Exchange the necessary details with everyone involved: names, contact information, driver’s license numbers, vehicle descriptions, license plate numbers, and insurance information. Take photographs of the vehicles, visible damage, the road, traffic signals, debris, skid marks, weather conditions, and the surrounding area. Wide shots establish context; close-ups capture damage.
If witnesses saw what happened, ask for their names and phone numbers. Their account may be useful if there is a dispute about how the accident occurred. Write down your own recollection while it is fresh, including the time, location, direction of travel, and sequence of events.
Do not rely on memory alone. A claim can take weeks or longer to resolve, and specific details are easier to preserve at the scene than recreate later.
How to File an Auto Claim Step by Step
1. Notify your insurer promptly
Contact your insurance carrier or agency as soon as practical after the loss. Many carriers allow reporting by phone, mobile app, online portal, or through an agent. Prompt notice matters because it allows the insurer to begin its review, inspect damage when needed, and explain the next steps before delays create additional complications.
When you report the claim, provide the facts you know without guessing. Be prepared to share the date and location of the incident, the vehicles and people involved, a description of what occurred, the police report number if one was issued, and photographs or other documentation. If you do not yet have every detail, report what you have and follow up with the remaining information.
Ask for the claim number and save it. You will likely need it when speaking with the adjuster, repair facility, rental car provider, medical providers, or your agent.
2. Review the coverages that may apply
The claim representative can explain which coverages are being considered, but it helps to understand the general distinctions. Liability coverage may respond to injuries or property damage you cause to others. Collision coverage may help repair or replace your vehicle after a crash with another vehicle or object. Comprehensive coverage can apply to non-collision events such as hail, theft, falling objects, or animal strikes.
Medical payments, personal injury protection, uninsured or underinsured motorist coverage, rental reimbursement, towing, and roadside assistance may also be relevant, depending on your policy and the circumstances. A deductible may apply to certain physical damage claims. If another driver is responsible, their insurer may ultimately handle some costs, but your own carrier can explain the options available under your policy.
Coverage decisions depend on policy terms, limits, exclusions, state requirements, and the facts of the loss. Do not assume that a specific expense is covered or uncovered before reviewing the claim with a qualified representative.
3. Protect the vehicle and prevent further damage
After reporting the incident, take reasonable steps to prevent additional damage. If a broken window leaves the interior exposed to rain, for example, temporary protection may be appropriate. If the vehicle is unsafe to drive, arrange towing rather than risking a second accident or further mechanical damage.
Keep receipts for reasonable expenses related to protecting the vehicle, towing, storage, or temporary repairs. Before authorizing major repairs, confirm the insurer’s inspection and repair process. Some carriers may inspect the vehicle in person, while others can begin from photos or a virtual estimate.
You generally have the right to select a repair shop, although the insurer may have preferred repair options. A preferred shop can offer convenience, but the best choice depends on your vehicle, the shop’s qualifications, warranty practices, scheduling, and your comfort level. For newer vehicles with advanced safety systems, ask whether the repair plan includes necessary sensor calibration and post-repair checks.
4. Work with the adjuster and keep records
An adjuster investigates the loss and evaluates covered damage. They may ask for a statement, photos, repair estimates, medical documentation, or permission to inspect the vehicle. Answer promptly and honestly, but take the time you need to provide accurate information. If you do not understand a request or a proposed settlement, ask for clarification.
Create one place for claim records. Keep the claim number, names and contact information for everyone you speak with, dates of conversations, emails, photos, estimates, receipts, rental records, and copies of police reports. A simple written log can prevent confusion when several parties are involved.
If the other driver’s insurer contacts you, you may provide basic identifying information and factual details. Be careful with recorded statements, broad medical authorizations, or settlement documents you do not fully understand. In injury claims or disputed-liability situations, it may be wise to speak with your insurer, agent, or a qualified attorney before agreeing to terms.
5. Understand the estimate, payment, and repair decision
The first repair estimate is not always the final amount. Once a shop begins work, hidden damage may be found. The shop can submit a supplement for additional covered repairs. This is common after collisions because internal components, mounting points, and safety systems may not be visible during an initial inspection.
If repairs cost more than the vehicle’s actual cash value, the insurer may determine that it is a total loss. In that case, ask how the vehicle value was calculated, whether any deductible applies, how a loan payoff is handled, and what happens to the vehicle title. Gap coverage, if you carry it, may be relevant when the loan balance exceeds the vehicle’s value.
For a rental vehicle, confirm the daily limit, maximum number of days, and any restrictions before making arrangements. Rental reimbursement coverage is useful, but limits vary. If you are pursuing the at-fault driver’s insurer, rental approval can take longer while liability is still under review.
Common Mistakes That Can Complicate a Claim
Waiting too long to report the loss is one of the most avoidable problems. Delays can make evidence harder to verify and may conflict with policy reporting requirements. Another frequent mistake is repairing or disposing of damaged property before the insurer has a chance to inspect it, unless immediate action is necessary to prevent further damage.
It is also wise not to post detailed accident information, photos, or opinions about fault on social media. A casual post can be misunderstood or used to challenge the facts of the claim. Keep your discussion focused on the appropriate parties: your insurer, agent, adjuster, repair shop, and any professionals advising you.
Finally, do not let a claim become a reason to ignore the policy itself. Once the immediate situation is under control, review your deductibles, limits, vehicle value, household drivers, and available endorsements. An accident often reveals whether the coverage you selected still fits your current circumstances.
When an Agent Can Make a Difference
Claims involve more than a damaged bumper. They can affect transportation, finances, work schedules, family routines, and confidence in the protection you purchased. An independent agent can help you understand the claims process, identify questions to raise with the carrier, and review whether your policy addresses gaps that become apparent after a loss.
First Mid Insurance Group can provide advisor-led support before and after an accident, helping you take the next practical step while keeping your broader protection in view. If you are facing a claim now, start with safety, document what you can, report the loss promptly, and keep asking questions until the path forward is clear.
Recent Comments